Trust Layer for Bank-Issued Stablecoins
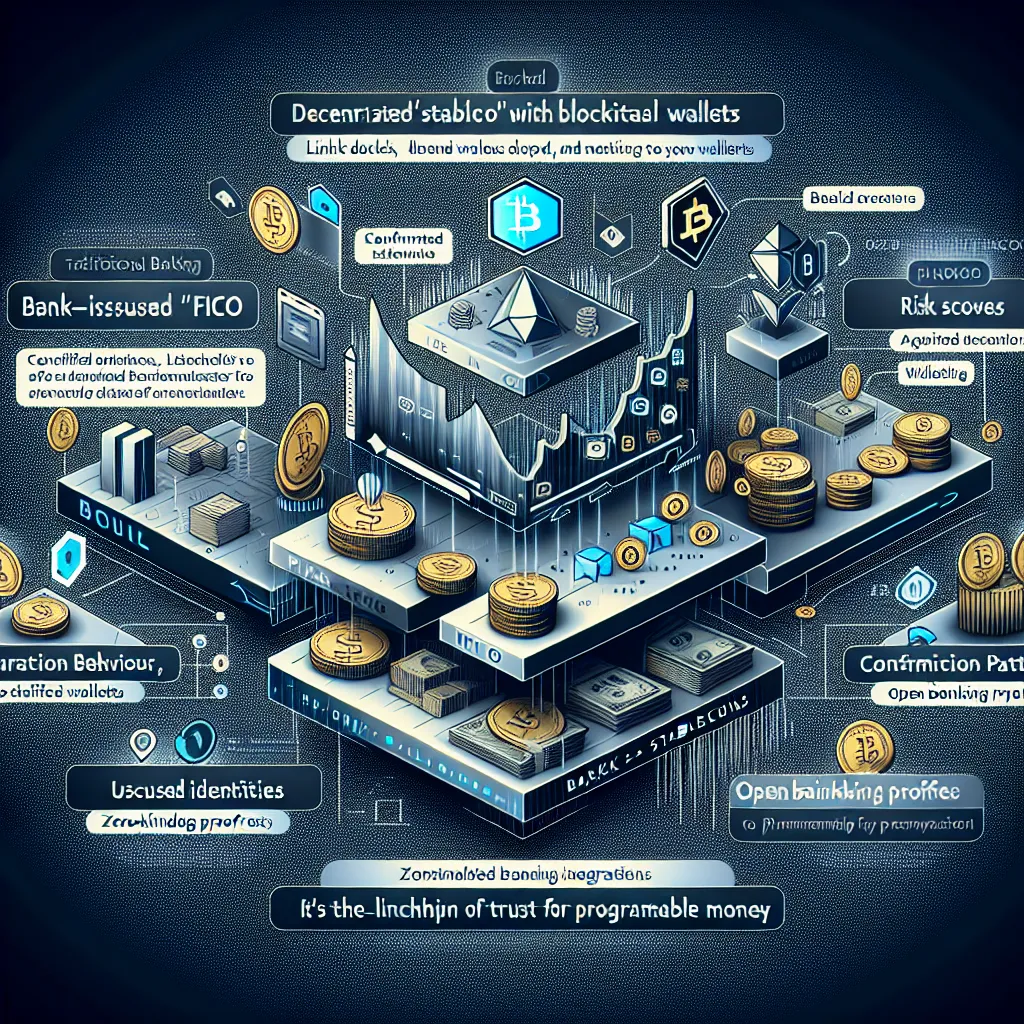
As banks begin issuing stablecoins under the GENIUS Act, there’s a massive blind spot: none of them know who their most valuable wallet holders are. Unlike traditional banking, on-chain money is pseudonymous. The opportunity? Build the first identity + creditworthiness layer for bank-issued stablecoins—a decentralized “Plaid + FICO” for wallets. It links wallet behavior, risk scores, transaction patterns, and verified identities to stablecoin flows. A bank can now see: this wallet holds $300K, regularly pays vendors, has no suspicious flags, and belongs to a verified business. It unlocks lending, better compliance, and high-trust transaction rails—all without violating user privacy. Built using zero-knowledge proofs and open banking integrations, this layer becomes the default identity rail for compliant on-chain finance. Example: A bank wants to offer 5% yield to “safe” wallets. This system helps them target and verify qualified holders programmatically. It’s the trust fabric for programmable money.
Description
No additional description provided.
The Pitch
With the issuance of stablecoins by banks under the GENIUS Act, a significant challenge has emerged in the realm of decentralized finance. Unlike traditional banking systems where account holders' identities and creditworthiness are readily available, the world of on-chain finance is characterized by pseudonymous transactions. This presents a unique opportunity to revolutionize the financial ecosystem by creating an identity and creditworthiness layer specifically for bank-issued stablecoins. Think of it as a decentralized version of services like Plaid and FICO, tailored for blockchain wallets.
The Problem
Banks deploying stablecoins are unable to discern the identity and creditworthiness of their wallet holders. This creates a blind spot in their ability to effectively and securely serve their clientele. Wallets in the blockchain world, while transparent in their transactions, do not inherently reveal the identity behind them. This lack of visibility increases risk, hinders the ability to offer targeted financial services such as lending, and complicates compliance efforts.
The Solution
The proposed solution is to develop a decentralized identity and creditworthiness layer. This system would integrate wallet behavior analytics, risk assessment scores, transaction patterns, and verified identities with stablecoin transactions. Utilizing technologies such as zero-knowledge proofs and open banking APIs, this solution maintains privacy while providing banks with the tools they need to assess and verify the wallets involved.
Product Details
This identity and creditworthiness layer will offer several key features:
1. Wallet Analysis: Insights into wallet holding patterns, transaction history, and risk levels. 2. Risk Scoring System: Assessment of wallets based on transaction behaviors and external credit data. 3. Identity Verification: Connect verified identities to wallets without compromising privacy. 4. Compliance Toolkit: Assist banks in meeting regulatory requirements by offering transparency in transactions. 5. Integration with Banking Systems: Seamless flow of data between traditional banking systems and blockchain environments using open banking standards.
Tools for Launching an MVP
To build and launch a Minimal Viable Product quickly, several tools and technologies can be utilized:
1. Blockchain Technology: Ethereum for smart contracts and stablecoin transactions. 2. Zero-Knowledge Proofs: Enhance privacy without sacrificing the ability to verify identity and transactions. 3. APIs: Open banking APIs to connect with traditional banking systems. 4. Data Analytics Tools: Platforms like Tableau or D3.js for visualizing wallet behaviors and risk assessments.
Go-To-Market Strategy
1. Targeted Partnerships: Collaborate with banks and financial institutions issuing stablecoins to pilot the system. 2. Strategic Alliances: Partner with blockchain platforms and fintech companies to enhance the offering and reach. 3. Phased Rollout: Begin with a beta version focusing on select banks, gather feedback, and refine the product before a wider launch. 4. Education and Marketing: Educate potential users on the benefits of the system through webinars, whitepapers, and case studies.
Business Model
The business will operate on a subscription and transaction-based model, charging banks and financial institutions that utilize the platform for identity verification and credit assessment services. Additional revenue streams can be incorporated through premium data analytics offerings and consulting services for compliance and integration support.
Conclusion
This identity and creditworthiness layer has the potential to transform the way banks interact with stablecoin holders, providing enhanced trust and enabling new revenue streams while maintaining the privacy and security that decentralized finance demands. As the first of its kind, this solution aims to set the standard for identity management and creditworthiness in the era of programmable money.