Mobile Platform for Informal Workers' Retirement Savings
The global workforce is shifting rapidly, with over 60% of workers operating in informal economies, often lacking access to retirement benefits or safety nets. These individuals, from ride-share drivers to market vendors to freelance creatives, typically have fluctuating incomes and little incentive—or mechanism—to consistently save for retirement. Traditional pension systems were not designed with their needs in mind. “Informal and gig workers often fall through the cracks of public retirement systems... leaving workers vulnerable in old age and perpetuating inequalities.” A startup could address this by offering a mobile platform that facilitates flexible, micro-contributions toward retirement or emergency savings. It would include features like round-up savings, matching incentives from NGOs or governments (modeled after Rwanda’s EjoHeza scheme), and portable digital accounts that follow workers regardless of employer. An example would be a fruit vendor in Lagos who can contribute $1 per day through their mobile wallet to build up long-term savings, automatically matched by a local fund. This enables dignity and security later in life without disrupting near-term cash flow.
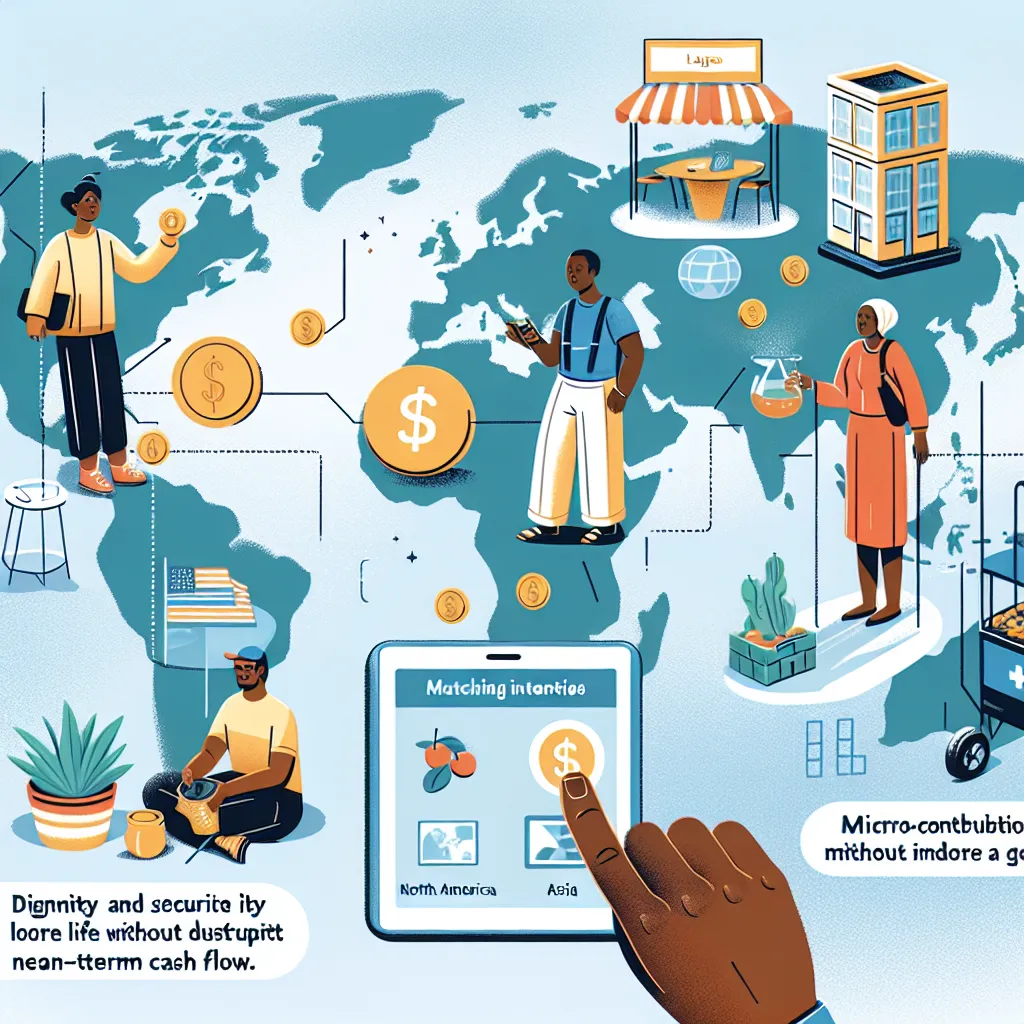
Description
No additional description provided.
The Pitch
The modern global workforce is undergoing a seismic shift. Over 60% of workers worldwide operate within informal economies, where traditional employment benefits, including retirement plans, are frequently unavailable. This demographic includes millions of individuals like ride-share drivers, market vendors, and freelance creatives. These workers often face irregular incomes, which in turn make it challenging to maintain consistent savings plans for their future. Traditional pension systems are not equipped to meet the unique needs of this diverse group, leaving them vulnerable in their old age and contributing to economic inequalities.
**Problem**
The key problem is the absence of a tailored retirement solution for informal and gig workers. Without access to formal savings structures, these individuals lack the incentive and mechanisms to consistently save. Moreover, public retirement systems often exclude them, leading to financial insecurity during the later stages of life. This predicament also exacerbates the existing economic disparity between different workforce sectors.
**Solution**
The solution lies in harnessing technology to create a flexible, accessible, and compelling savings platform that caters specifically to the informal workforce. This startup would develop a mobile app to enable users to make micro-contributions towards their retirement or emergency savings. Features would include:
- **Round-up Savings:** Automatically round up daily expenses and transfer the difference to a savings account. - **Matching Incentives:** Partner with NGOs or governments to provide contribution matches, inspired by successful models like Rwanda's EjoHeza scheme. - **Portable Accounts:** A digital account that remains with the individual, providing continuity despite changes in employment.
**Product Details**
The mobile platform focuses on simplicity and accessibility, allowing users to easily initiate and manage their savings. Key functionalities would include:
- **User-Friendly Interface:** Simple, intuitive design to appeal to a wide user base, accommodating varying levels of tech-savviness. - **Flexible Contributions:** Enable users to set aside as little as $1 per day, with options to adjust contributions based on income variability. - **Automated Processes:** Implement automated transfers and savings to reduce friction and encourage consistent participation. - **Robust Security:** Employ secure technologies to protect sensitive user data and account details.
**Tools for Launching MVP**
- **Platform Development:** Use development frameworks like React Native for cross-platform mobile application compatibility. - **Payment Integration:** Integrate with mobile wallet services for seamless deposits and withdrawals. - **Data Analytics:** Employ tools like Google Analytics to monitor user engagement and behavior. - **Security Solutions:** Utilize services like AWS for secure data storage and management.
**Go-to-Market Strategy**
- **Partnerships:** Establish relationships with local NGOs, government bodies, and financial institutions to provide matching incentives and amplify reach. - **Community Engagement:** Engage community leaders and influencers within informal sectors to build trust and promote the platform. - **Educational Campaigns:** Implement campaigns to raise awareness about the importance of savings and how users can leverage the platform to secure their future. - **Pilot Programs:** Launch in select cities with high informal workforce density to fine-tune features and marketing approaches before broader rollout.
**Business Model**
- **Subscription Fees:** Charge a nominal monthly fee for platform access and services. - **Transaction Fees:** Implement minimal fees on transactions or withdrawals to sustain operational costs. - **Partnership Revenue:** Generate income through partnerships with matching funds or financial institutions providing value-added services. - **Impact Investments:** Seek partnerships with impact investors looking to drive positive social change, which can provide funding while meeting their social responsibility goals.
In conclusion, this initiative seeks to bridge the gap in retirement planning for the informal workforce through an innovative, inclusive, and technologically-driven solution. By focusing on the specific needs and circumstances of these workers, the platform aims to foster financial security and dignified living for all individuals, irrespective of their employment status.