Financial Circuit Breakers for AI Transactions
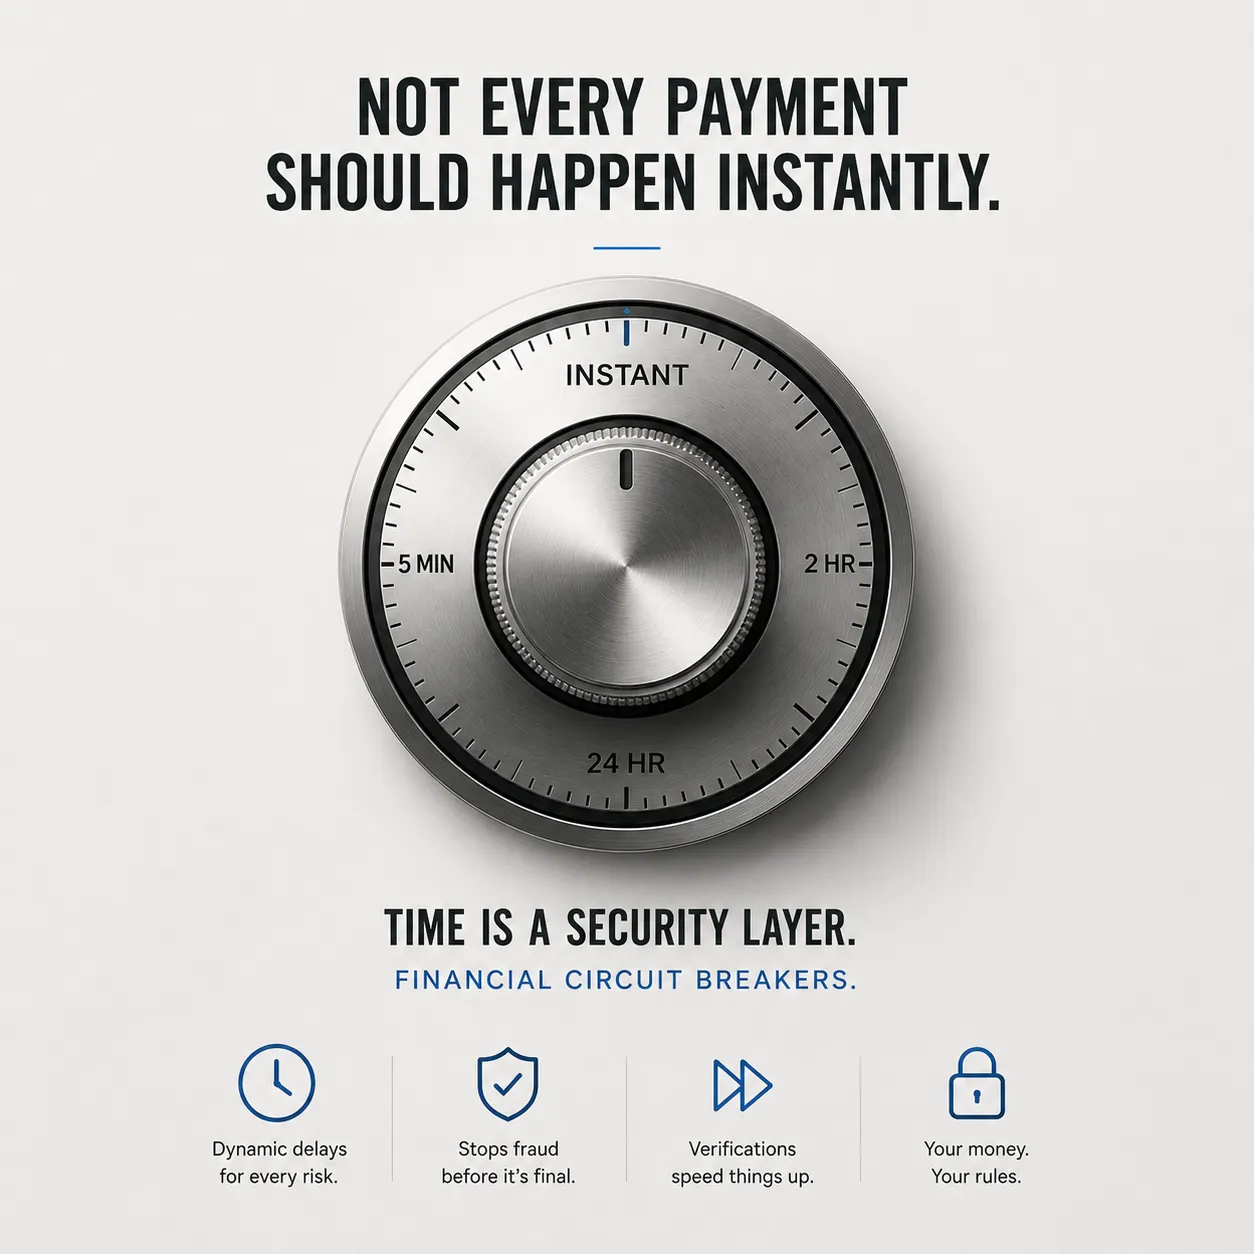
Money is being given to AI agents that can spend, transfer, trade, and eventually negotiate without a human clicking approve, but financial security still treats transactions mostly as things that happen instantly or get blocked. Financial Circuit Breakers would make time itself a security layer, dynamically changing how quickly money can move based on the risk of the action. A $40 recurring purchase clears instantly; $5,000 to a new recipient waits five minutes; an agent attempting an unprecedented $50,000 transfer waits two hours, with the delay disappearing early if independent verification arrives. This matters now because autonomous finance dramatically increases the speed at which mistakes and fraud can become irreversible. Instead of asking only can this transaction happen?, financial infrastructure gets a second control: when should it become final?
Description
No additional description provided.
The Pitch
Autonomy changes the unit of financial risk from the transaction to the sequence. Humans make suspicious payments one at a time; agents can create cascades. The dangerous event is not merely a $5,000 transfer, but a chain of individually permissible actions that becomes catastrophic before anyone notices. A company that understands money movement as a temporal pattern, not a binary permission, would sit at a new choke point in financial infrastructure.
The memorable insight is that delay can be a product, not friction. Traditional finance treats waiting as a failure of speed, but in autonomous finance, selective waiting becomes a feature of trust. The best security control is not always a harder wall; sometimes it is a short, intelligent pause that preserves optionality. Once money is gone, the system has to litigate, insure, reverse, or absorb the loss. Before it is gone, the system only has to decide whether to let time pass.
This would also be compelling because it aligns the incentives of parties that usually disagree. Banks want fewer irreversible losses, users want less paranoia, merchants want legitimate payments to clear, and agent platforms need permission to act without being treated as malware. A timing layer can satisfy all of them because it does not require making every transaction harder. It makes ordinary behavior feel fast and reserves skepticism for moments when speed is itself the risk.
The business becomes more interesting as it accumulates memory. The valuable asset is not just a rule engine that says “wait five minutes.” It is a living map of what normal financial agency looks like across counterparties, devices, accounts, models, wallets, and contexts. In a world where AI agents may be created cheaply and impersonation becomes routine, reputation will attach less to identities alone and more to behavioral continuity. Knowing whether an action is merely new, or new in a dangerous way, becomes a defensible form of intelligence.
The deeper shift is that financial infrastructure has spent decades optimizing for authorization, but autonomous money will require pacing. As machines become capable of moving value faster than institutions can reason about it, the scarce commodity is not execution speed; it is reversible time. A company that sells precisely that—without making finance feel slow—could become one of the quiet control surfaces beneath the agent economy.