Auction Marketplace for Consumer Banking Deposits
Banks spend billions advertising savings rates, bonuses, credit cards, and investment products hoping consumers move money to them, while consumers leave trillions sitting wherever they already bank. Personal Capital Auction flips that market: financial institutions continuously bid for the right to hold or use your next dollar. A consumer tells their agent to keep $25,000 liquid and maximize everything above it; banks, brokers, Treasury products, debt providers, and other eligible institutions submit offers, and the agent automatically routes capital to the best risk-adjusted deal. A bank might offer 4.4%, another $500 for a three-month deposit, while paying down a credit card produces an effective 19% return. As AI makes continuous financial optimization possible, customer acquisition could shift from institutions buying ads to institutions bidding directly for your money.
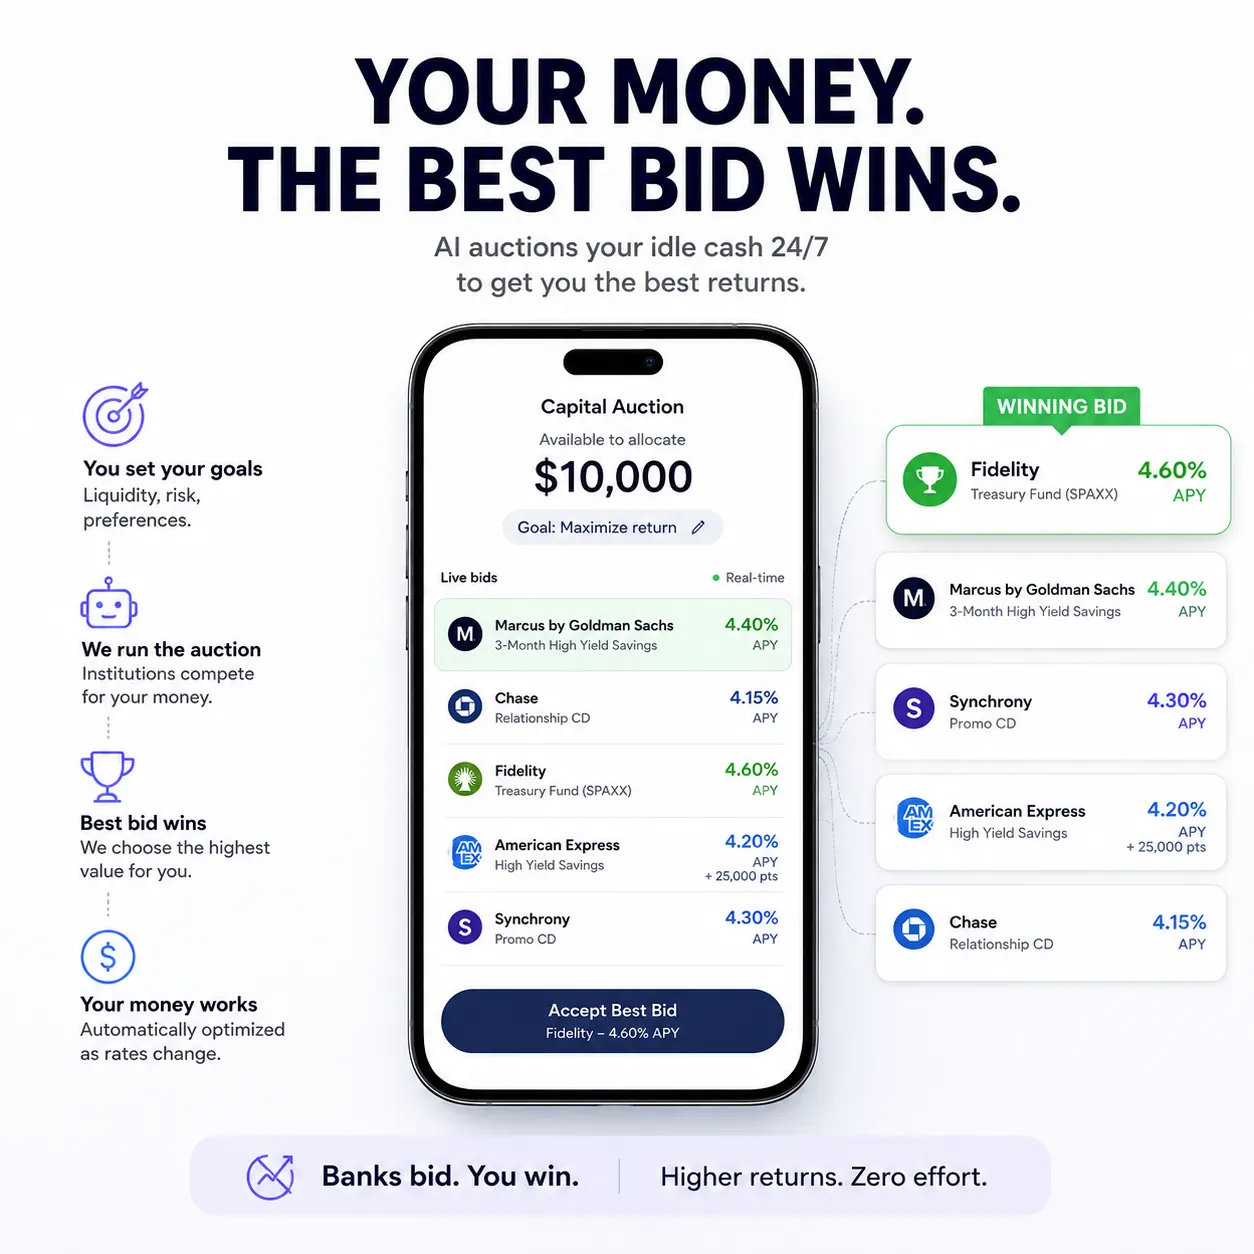
Description
No additional description provided.
The Pitch
Consumer finance is still organized around attention, not capital. Banks compete to be remembered at the right moment: when a person opens an account, refinances a mortgage, sees a bonus offer, or finally gets annoyed enough to move money. But money itself is measurable, movable, and economically valuable. If a trusted agent can represent the consumer continuously, the market no longer has to wait for the consumer to notice a better offer. The dollar becomes the object being competed for, not the customer’s distracted mind.
This would be especially powerful because financial inertia is not a small inefficiency; it is the business model of much of retail banking. Institutions profit from balances that remain underpaid, debts that remain unoptimized, and customers who do not compare alternatives after the initial account opening. A system that repeatedly asks “what is the best use of this marginal dollar right now?” attacks that inertia at its source. The consumer does not need to become more financially sophisticated; their money simply stops being passive.
The marketplace could also reveal a truer price for deposits and customer capital than today’s advertised rates do. A bank that needs deposits in a specific geography, duration, balance size, or customer profile could bid precisely instead of broadcasting generic promotions. That makes the market more efficient for institutions as well as consumers: acquisition dollars become yield paid to the customer, and the offer can vary with the institution’s actual need for funds. In that sense, the product turns marketing expense into a financial instrument.
The defensibility would come from being the trusted decision layer between the consumer and the financial system. Once an agent understands cash needs, tax constraints, debt obligations, risk tolerance, account permissions, and household habits, it becomes painful to replace. The winning company would not merely show better offers; it would accumulate the context required to know when an offer is truly better. In finance, the hard problem is often not finding yield, but knowing which yield is worth taking.
The most interesting consequence is that this could change how loyalty works in banking. Today loyalty often means staying put despite better alternatives. In this model, loyalty shifts from an institution to an instruction: preserve liquidity, reduce risk, and make each dollar work harder. The bank no longer owns the relationship by default. The consumer’s agent does.